
The situation
A property developer thought their financing was locked in for their next site. It fell through, leaving them $250K short on the deposit. They had a sale waiting to settle, but the option was up on Friday, and no deposit meant no site. They only needed the money until the sale came through.
The asset
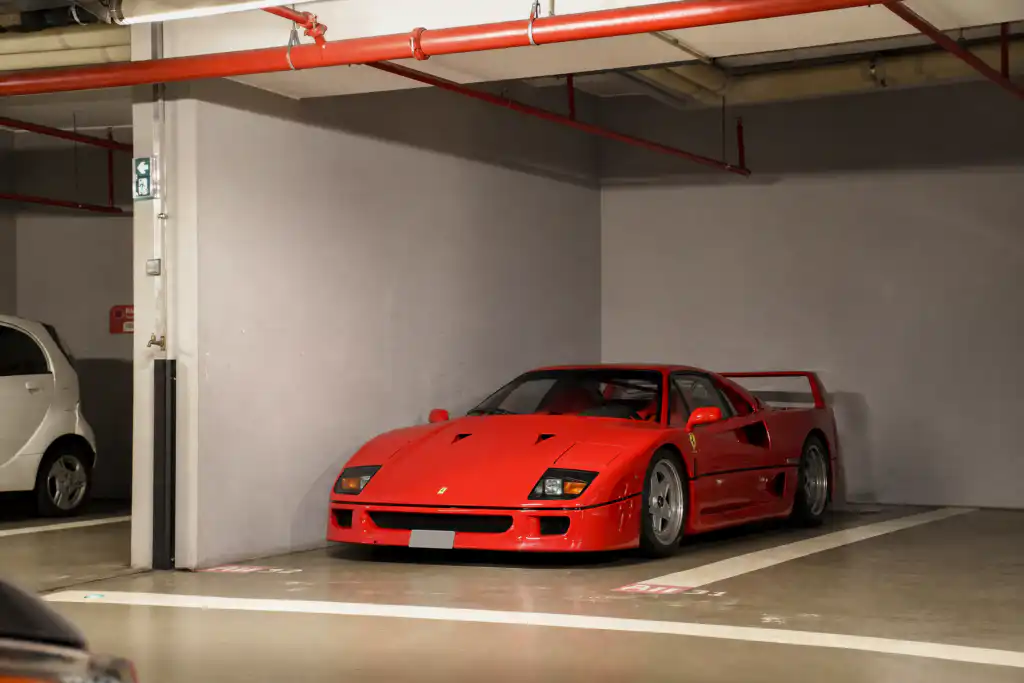
A Ferrari, owned outright.
The need
A $250K loan to cover the shortfall and secure the site before the Friday deadline.
The structure
A Park It facility. ABL valued the Ferrari and advanced $250K against it. Funds are released once the asset is secured, and the Ferrari was secured the same day. The car is parked securely for the loan term and stays untouched until repayment. The intended term is one month. The developer can extend at any time, up to 9 months, and after month one pays by the day for what they use. There is no penalty to exit at any point after month one.
The outcome
The developer exercised the option and secured the site. The loan is running now, with repayment set for when the sale settles, and the Ferrari comes back when it does.
Why this deal worked
Three things had to be true for this deal to work. They’re the same three things every Park It deal needs:
- An asset with real value, owned outright. The Ferrari wasn’t financed or tied up in another loan, so it could be lodged cleanly.
- A genuine short-term exit. The developer wasn’t borrowing their way out of a permanent problem. They had a specific event, the sale settling, and repayment waiting on the other side.
- The right partner around the deal. The broker who led this deal brought it to us when the financing fell over.
Asset-based lending isn’t the answer to every business problem. It’s a specific tool for a specific moment: when timing matters more than rate, when an asset is available, and when there’s a clear way out. For more on the category, read our complete guide to asset-based lending.
Got a client with an asset and a short-term gap?
If your client owns an asset outright and needs cash for a defined short-term purpose, that’s an ABL conversation. Here’s how asset based lending works. We look at what they own, not their credit file or P&L. Same shape as a home equity loan, except the security is an asset they already own.
Get Accredited